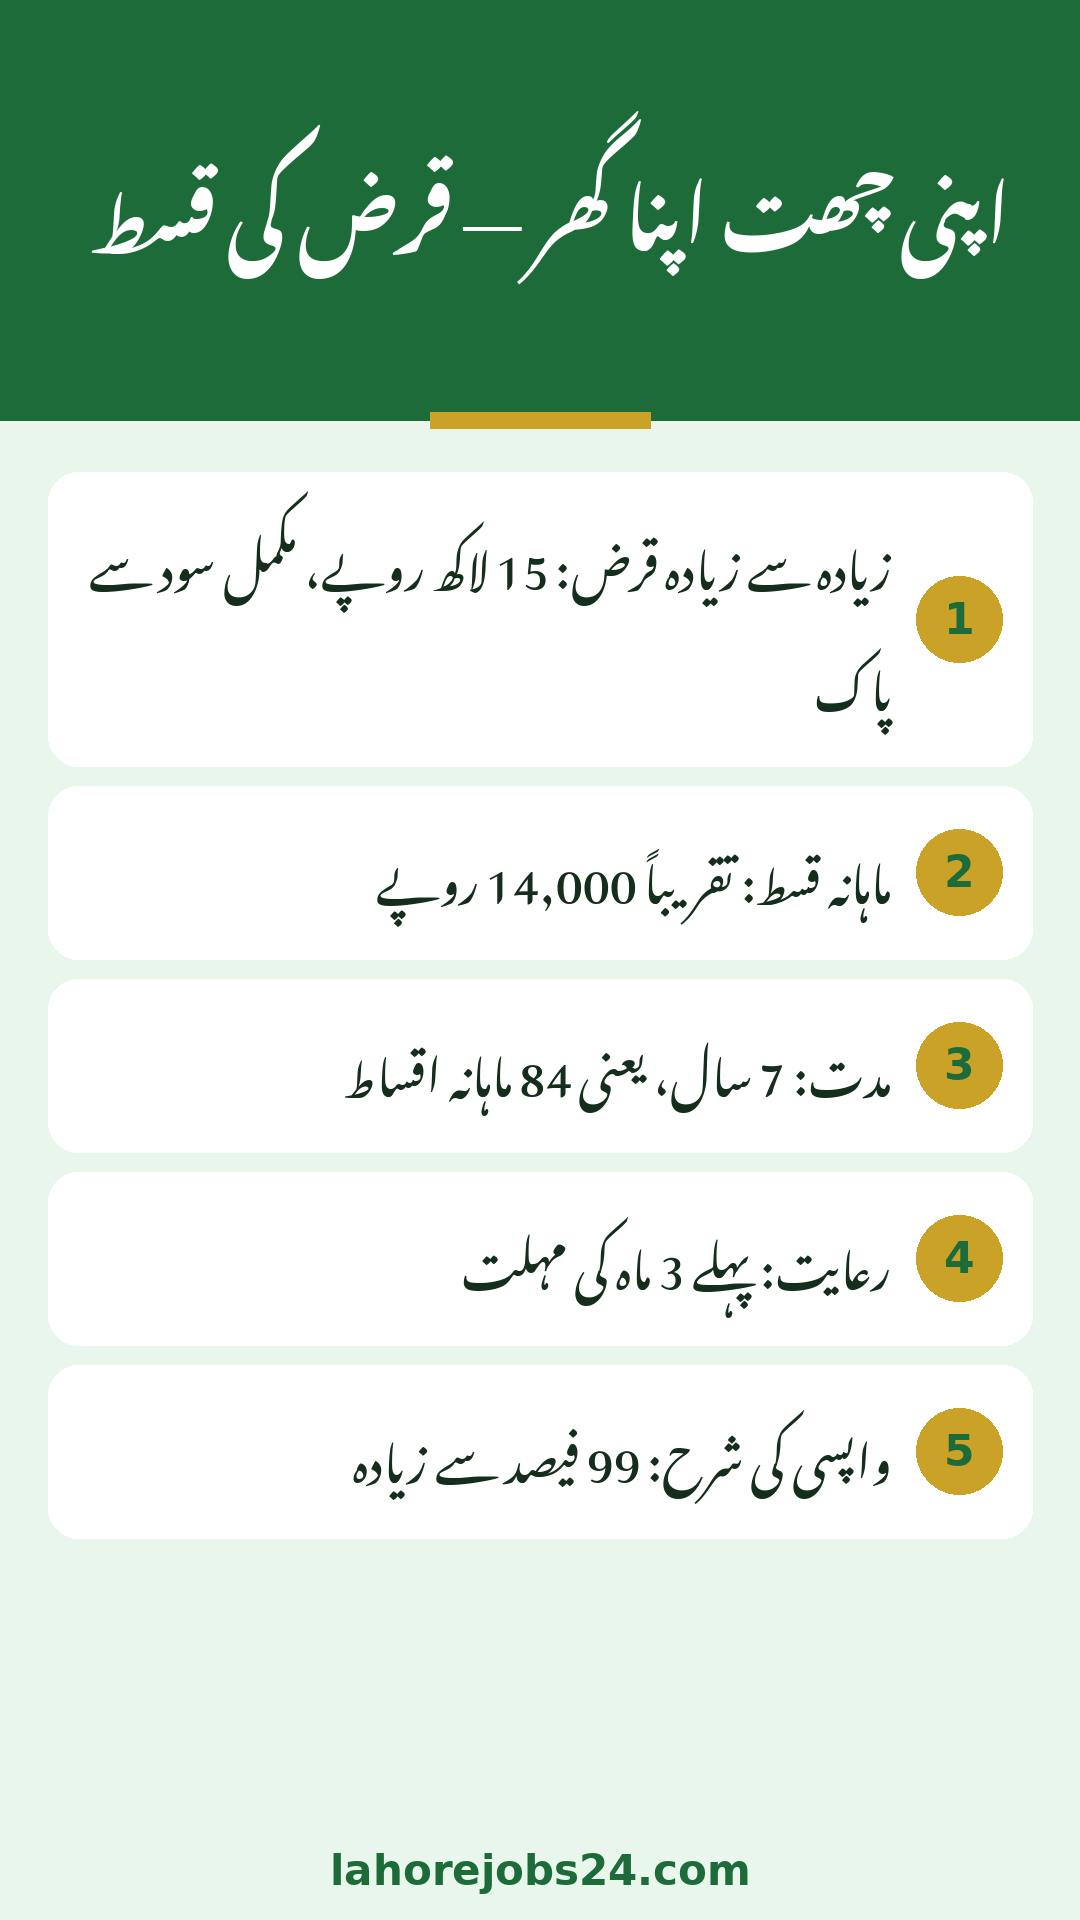
The Apni Chhat Apna Ghar loan is simple on purpose: borrow up to Rs 1.5 million, pay zero markup, and return the money in easy monthly instalments of around Rs 14,000 over seven years. There are no hidden charges, no balloon payments and no fine-print traps in the headline terms. This guide explains the instalment maths, the grace period, the early-repayment rebate and why more than 99 percent of borrowers repay on time.
Loan term
Programme figure
Maximum loan
Rs 1,500,000 (Rs 15 lakh) for house construction
Markup
Zero, fully interest-free
Monthly instalment
Around Rs 14,000 per month as quoted in current guides
Repayment period
7 years (84 monthly instalments)
Grace period
First 3 months waived, as described in current guides
1. Apni Chhat Apna Ghar Rs 15 Lakh Loan: What Zero Markup Means
Interest-free means exactly what it says. You borrow the principal and you return the principal, with the Government of Punjab absorbing the financing cost and the Bank of Punjab disbursing the loan on the government’s behalf. For the borrower, there is no markup, no service charge on the loan itself and no compounding interest building up behind the monthly instalment. Compare that with a normal bank home loan, where markup can nearly double what you pay back over the years, and the difference becomes obvious: here the total cost of borrowing to you is the loan itself.
Programme literature also describes the financing in three tiers, so families can borrow only what their construction stage actually needs: Rs 500,000 for small additions, Rs 1,000,000 for an upper portion or additional storey, and Rs 1,500,000 for full construction or major extension on your own plot. All three tiers carry the same headline terms, and the money is not handed over in one lump sum. It is released in stages tied to construction progress, which protects both the borrower and the programme from misuse and keeps the build moving in step with the money.
The instalment figure most current guides quote is around Rs 14,000 per month, paid over seven years, which is 84 months. It is deliberately set at a level a daily-wage or small-salaried household can manage without skipping essentials. The Chief Minister herself has pointed to this small instalment as a reason the programme’s recovery rate is above 99 percent: when the monthly burden is realistic, families pay, and when it is crushing, they default. The programme chose realistic.
Instalment: around Rs 14,000 per month, as quoted in current programme guides.
Duration: 7 years, or 84 monthly instalments for the full term.
Fixed character: the instalment does not rise with inflation or policy rates.
Affordable by design: small enough for a modest household budget to sustain.
Your personal schedule: confirm the exact instalment on your own sanction letter, because tier and approved amount affect your plan.
A word of honest caution belongs here. Programme guides quote the Rs 14,000 figure as an approximate monthly amount, and some summaries describe a government subsidy model in which the beneficiary repays only part of the construction cost. Do not treat a headline figure as your personal contract: your sanction letter and the Bank of Punjab schedule for your approved tier are the documents that fix what you actually pay each month. If a branch officer quotes you a different product, with markup or a commercial rate, that is not the Apni Chhat Apna Ghar loan, and you should ask for the programme terms in writing.
Most current scheme guides describe a three-month grace period at the beginning of the loan. In plain words, you get a short breathing space after disbursement before the monthly instalments begin, so you can settle your construction and your household budget first. The first three months are waived in the usual description, and the regular schedule starts after that window.
Purpose: breathing space right after the loan is disbursed.
Length: 3 months, as described in most current guides.
Use it well: organise your construction plan and monthly budget in this window.
After it ends: the regular monthly instalment schedule begins.
Treat it as preparation time, not free money, because the instalments that follow last seven years.
Families who plan their spending in these three months find the seven-year journey much easier than those who do not. Set the instalment aside in your monthly budget before the first payment falls due, agree who in the household is responsible for paying it, and keep the payment receipt for every month. A clean payment record is also your protection if any dispute about your account ever arises.
4. Apni Chhat Apna Ghar Early Repayment Rebate: Pay Early, Save More
Here is a term many borrowers miss, and it comes straight from the official portal. If you repay your full outstanding principal early, you earn a rebate, which means a discount on what you owe. According to the official portal, full early repayment earns a 20 percent rebate within years 1 to 3, and a 10 percent rebate within years 4 to 6, with standard repayment applying after year 6.
An example makes it clear. Suppose after two years you still owe Rs 1,000,000 of principal and you arrange the full amount. With the 20 percent rebate, you would pay Rs 800,000 and the remaining Rs 200,000 is waived. That is a genuine reward for clearing the loan early, and it is published on the programme’s own portal. It also explains why families who receive a lump sum, from savings or a family contribution, should ask the bank about the rebate before simply paying instalments ahead: a full early settlement can be worth far more than the same money spread across future months.
Do not confuse early repayment with overpaying an instalment. Paying a little extra each month is not the same as a full early settlement, and the rebate applies to full repayment of the outstanding principal within the stated years. Ask the Bank of Punjab to confirm the rebate calculation in writing before you arrange the money, so the discount is recorded on your account.
5. Apni Chhat Apna Ghar Loan Eligibility: Who Can Borrow
The instalment plan only helps if you qualify in the first place, so the eligibility rules deserve a clear summary. Applicants are expected to be permanent residents of Punjab, verified through the CNIC address, and to be the head of the household as per NADRA records. You must own a residential plot of 1 to 5 marla in urban areas, or 1 to 10 marla in rural areas, and your household income should be roughly Rs 60,000 a month or less, with a PMT score of 60 or below preferred. A clean record matters too: no criminal record and no history of defaulting on bank loans.
Eligibility point
Requirement
Residence
Permanent resident of Punjab, verified through CNIC
Plot size
1 to 5 marla urban, or 1 to 10 marla rural
Income guide
Household income around Rs 60,000 a month or less; PMT 60 or below preferred
Record
No criminal record, no bank loan default history
Two common misunderstandings need correcting. First, a proposal reported in January 2025 to raise the cap to Rs 2 million was never implemented, so the maximum loan remains Rs 1.5 million. Second, applications go only through the official portal or the district registration desks, never through a paid agent. If anyone offers to secure your loan for a fee, that offer is not part of the programme.
A recovery rate above 99 percent is extraordinary for any loan programme, and it is worth understanding because it tells you the loan is genuinely manageable. The small instalment is the first reason, zero markup is the second, and the three-month grace period is the third, because it prevents early defaults before construction is organised. Verification is the fourth reason: only genuinely eligible families enter, so repayment capacity is real rather than assumed. Ownership pride is the fifth: families building their own home protect it fiercely.
Small instalment: around Rs 14,000 fits a modest household budget.
Zero markup: every rupee paid reduces the actual debt.
Grace period: the three-month breathing space prevents early defaults.
Verification: only genuinely eligible families enter, so repayment capacity is real.
Ownership pride: families building their own home protect it fiercely.
Expansion effect: good repayment created room for new borrowers, most recently with Rs 60 billion approved for 40,000 more loans on 19 October 2026.
That discipline is also why the cabinet keeps expanding the programme. Each round of on-time repayment proves the model works, and each expansion gives another group of plot-owning families the same chance. If you are already a borrower, your on-time instalments are part of that record. If you are applying, the same discipline is what will carry you through seven years of payments to a house that is fully your own.
For official details and the application portal, visit acag.punjab.gov.pk, or call the toll-free helpline on 0800-09100. The official portal is also where the early-repayment rebate terms are published, so check them there before arranging any early settlement.
Conclusion
The Apni Chhat Apna Ghar loan gives you up to Rs 1.5 million with zero markup, around Rs 14,000 a month for seven years, a short grace period at the start, and a real rebate if you repay early. It is the most borrower-friendly housing loan in Punjab’s history, but only if you treat the headline figures correctly: confirm your personal instalment on your sanction letter, use the grace period to organise your budget, pay on time every month, and ask about the rebate before any early settlement. A house built on those habits is not just a roof; it is an asset your family keeps.
FAQs
What is the monthly instalment for the Apni Chhat Apna Ghar loan?
Around Rs 14,000 per month, paid over seven years (84 months), as quoted in current programme guides. Confirm your exact instalment on your sanction letter, because your approved tier affects your schedule.
Is the Apni Chhat Apna Ghar loan really interest-free?
Yes. It is fully interest-free. You repay only the principal you borrowed, the government bears the financing cost, and the Bank of Punjab disburses the loan under the programme’s rules.
What is the grace period for the loan?
Most current guides describe a three-month grace period at the start, with the first three months waived, before the regular monthly instalment schedule begins.
What is the early-repayment rebate?
According to the official portal, full early repayment of the outstanding principal earns a 20 percent rebate within years 1 to 3, and a 10 percent rebate within years 4 to 6. After year 6, standard repayment applies.
Can I get Rs 2 million under this scheme?
No. A proposal to raise the cap to Rs 2 million was reported in January 2025 but was never implemented. The maximum loan remains Rs 1.5 million.
Where do I apply for Apni Chhat Apna Ghar?
Apply only through the official portal or your district registration desk. Never pay an agent, and never trust a third-party website claiming to register you.
Shahzad Sahil is the editor of lahorejobs24.com, covering government jobs, private jobs, bank jobs, results and education news for Lahore and Punjab, with information verified from official sources.