The Punjab Kisan Card gives farmers up to Rs 150,000 per season at zero interest for seed, fertilizer and pesticides. It is a powerful facility, but it is not open to everyone. The card belongs to Punjab’s small and medium farmers, and eligibility is checked against real land records, a real CNIC and a clean bank history. This article lays out the 2026 eligibility rules plainly, explains how the loan amount is worked out, and tells you honestly which applications get refused and why.
Eligibility pillar
Rule for 2026
Why it matters
Residency and CNIC
Resident of Punjab with a valid CNIC
Scheme is for Punjab farmers only
Land holding
1 to 12.5 acres, PLRA-verified
Loan size is tied to verified land
Mobile SIM
Registered against the farmer’s own CNIC
Alerts and verification go to the farmer
Bank record
Must not be a defaulter of any bank
A default is the commonest refusal reason
Eligibility at a Glance for Punjab Farmers
Four pillars carry the whole approval. If all four stand, your application has a strong foundation. If any one fails, the application will struggle, however genuine your farming work may be.
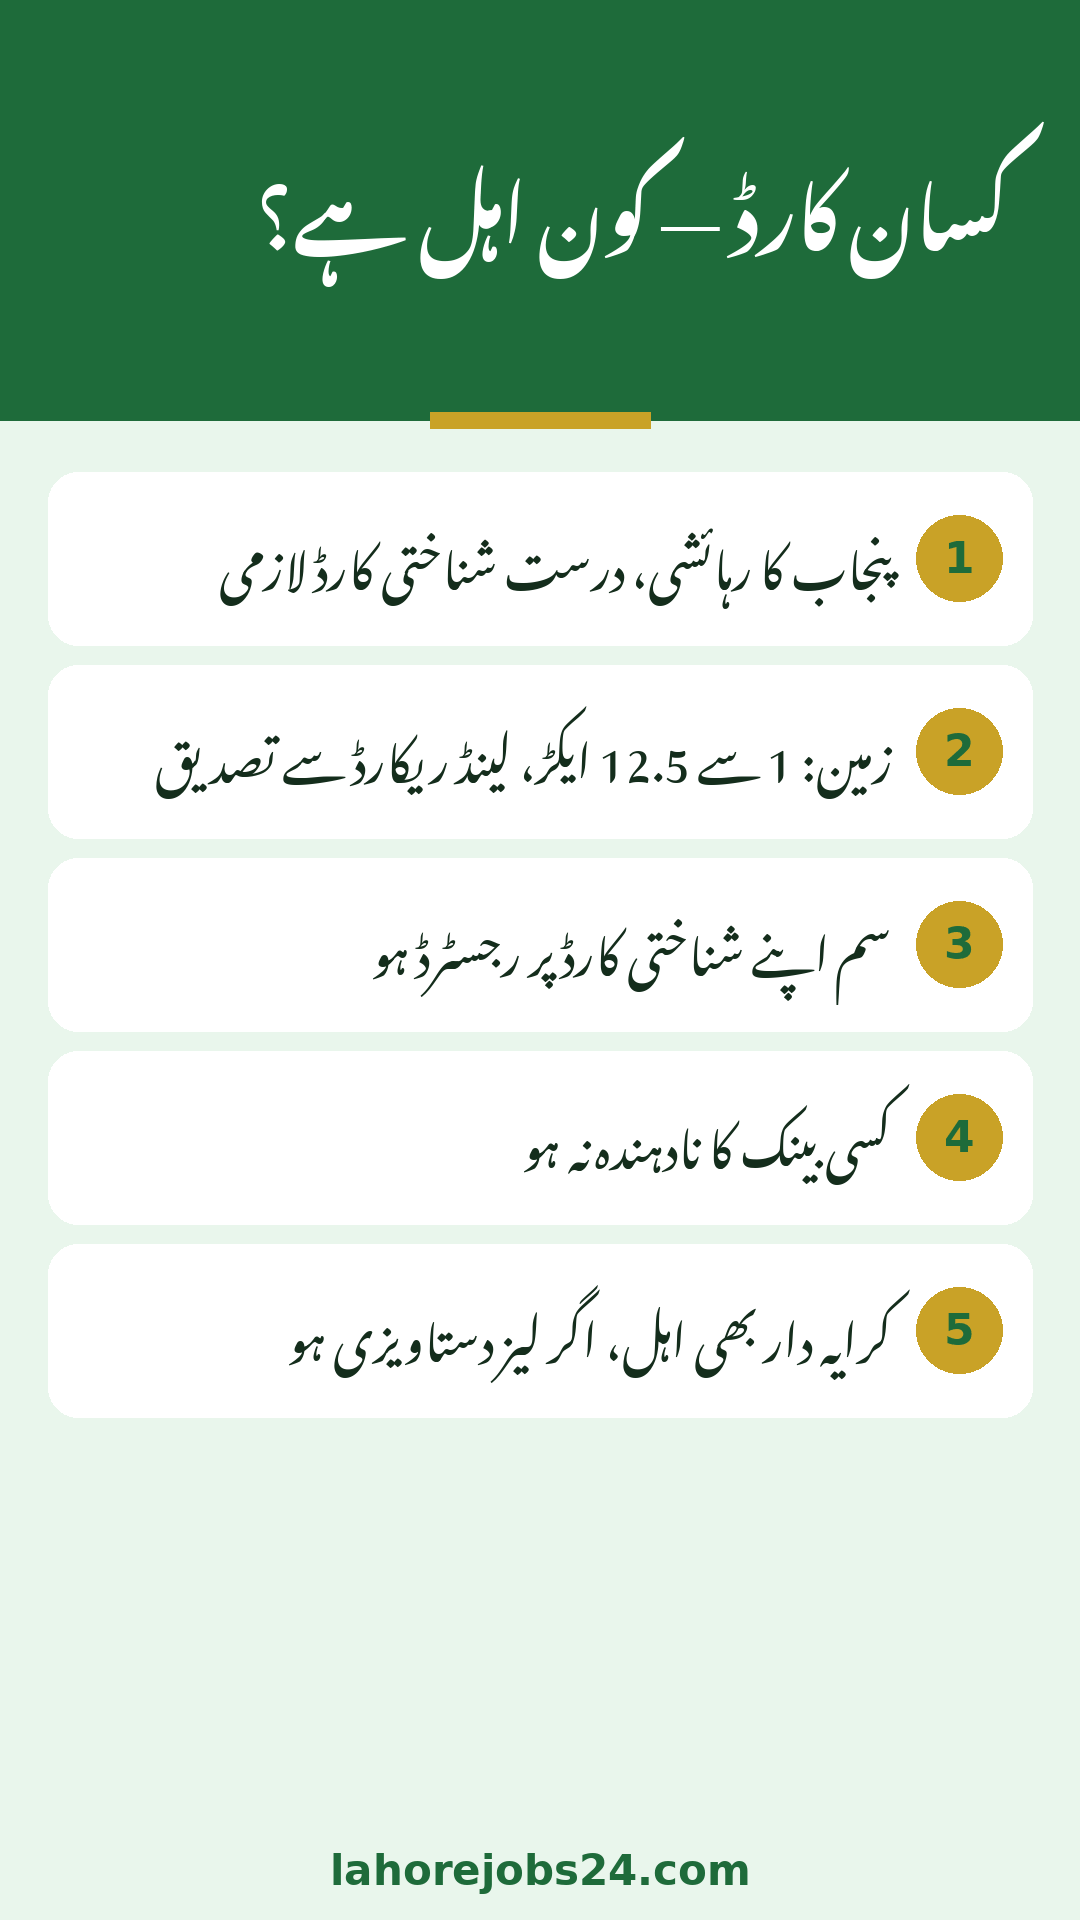
Residency: you must be a resident of Punjab, with a valid CNIC.
Land: you must hold between 1 and 12.5 acres of agricultural land, verified through the Punjab Land Records Authority.
Tenancy: tenant farmers can apply where their tenancy or lease is properly documented and verified.
Mobile: your SIM must be registered against your own CNIC, not a family member’s or a shopkeeper’s.
Bank record: you must not be a defaulter of any bank.
Identity match: the name, CNIC and mobile details in your application must match official records exactly.
The Land Rule: 1 to 12.5 Acres Explained
Land is the anchor of the Kisan Card, because the loan is sized to the land and secured against the record. The scheme accepts holdings from 1 acre up to 12.5 acres. Below 1 acre, the holding is too small for a seasonal input loan of this design. Above 12.5 acres, the farmer is considered large enough to access normal commercial finance, so subsidised funds stay with the smaller growers who need them most.
Minimum: 1 acre of agricultural land, verified in official records.
Maximum: 12.5 acres of agricultural land, verified in official records.
Verified by: Punjab Land Records Authority records, not by anyone’s word.
Common block: a misspelled name in the land record.
Common block: an unsettled inheritance entry or a mutation still pending.
Smart move: correct land records first, then apply, rather than applying with a known mismatch.
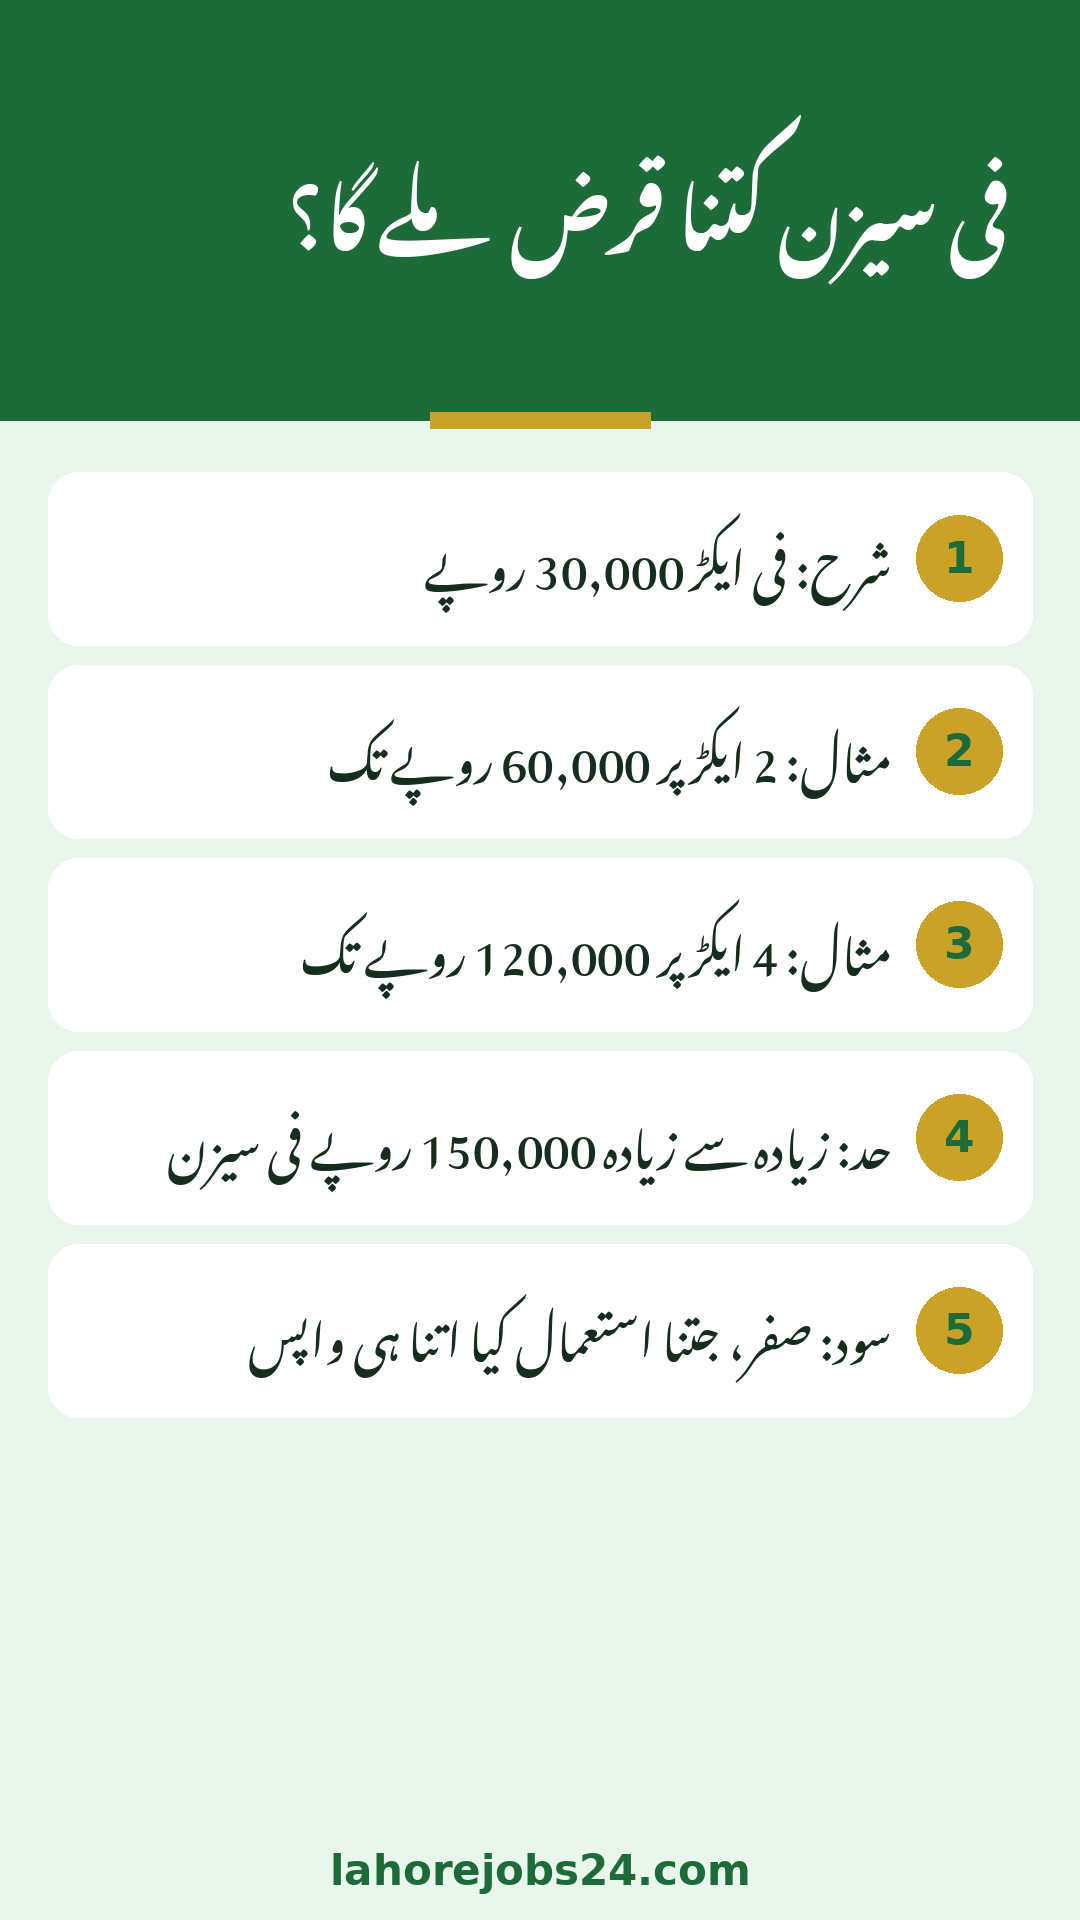
Eligibility decides whether you get in, and this rule decides how much you get. The facility is Rs 30,000 per acre of your verified land, up to a season ceiling of Rs 150,000.
Rate: Rs 30,000 per acre of verified land.
Example: a farmer with 2 acres qualifies for up to Rs 60,000.
Example: a farmer with 4 acres reaches Rs 120,000.
Ceiling: at 5 acres the farmer hits Rs 150,000, the season maximum.
Above 5 acres: holdings up to 12.5 acres stay at the same Rs 150,000 cap.
Refresh: the same loan refreshes every season, once the previous bill is paid on time.
That cycle is the real power of eligibility. One approval opens season after season of affordable input finance, provided you repay on time. Pay your bill, and the next season’s amount reloads to your card, within 48 hours of payment in the current cycle.
Interest-Free Means Exactly That
Say the words carefully, because they carry the whole promise of the scheme. Interest-free means you pay back exactly what you used, and nothing on top. If your season usage was Rs 92,000, your bill is Rs 92,000, and that is the end of it.
Interest charged: zero, the loan is completely interest-free.
Hidden charges: no markup and no hidden service charge on the facility.
Season length: 6 months of card use per season.
Repayment grace: 1 month after the season closes to settle the bill.
Markup cost: borne by the government, not by the farmer.
Comparison: an informal lender’s advance quietly eats a large share of the harvest, while this card does not.
The government absorbs the markup cost so that the facility reaches farmers who could never carry a commercial bank loan through a full crop season. That is why the card is worth protecting: misuse it, and you risk losing a facility that no private lender will match.
What the Loan Can and Cannot Buy
The loan is input money, and it flows through farming channels. Your card works like a debit card at registered agri-input dealers, where you purchase seed, fertilizer and pesticides for the season. That focus is deliberate, because it keeps the loan tied to the crop it finances.
Buy: seed for your crops, from registered dealers.
Buy: fertilizer and pesticides for the season, from registered dealers.
Use: the card like a debit card at registered agri-input dealers.
Watch: free SMS alerts on your registered mobile track every transaction.
Not for: machinery purchases or general non-farm spending.
Not for: house building, household cash, or other non-input uses.
Honesty matters in this section, because a refused application hurts most when it surprises you. Most refusals come from a small number of predictable causes, and most of them can be fixed before you apply.
Bank default: the commonest refusal reason, a default on record against the farmer’s name.
Unverifiable land: land that the land authority cannot verify in your name.
SIM mismatch: a SIM registered in someone else’s name, not the applicant’s.
Expired CNIC: a CNIC that has expired, or details that do not match the CNIC record.
Wrong region: applying from outside Punjab, or with non-agricultural land.
Undocumented tenancy: a tenant claim with no verified lease or tenancy paper.
Two traps are worth naming again. One is applying with a SIM in another person’s name, because every alert and verification step then goes to the wrong person. The other is rushing to apply before a land record error is fixed, because the scheme will believe the record, not your explanation.
Verified land
Loan at Rs 30,000 per acre
Season ceiling applied
1 acre
Rs 30,000
No, below the ceiling
2 acres
Rs 60,000
No, below the ceiling
4 acres
Rs 120,000
No, below the ceiling
5 acres or more, up to 12.5 acres
Rs 150,000 or more by rate
Yes, capped at Rs 150,000
Conclusion
Punjab Kisan Card eligibility rests on four clear pillars: Punjab residency with a valid CNIC, 1 to 12.5 acres of verified land, a SIM in your own name, and a clean bank record. Meet those, and you can access up to Rs 150,000 per season, interest-free, for seed, fertilizer and pesticides, refreshed each season when you repay on time. Check your land record first, fix any mismatch, keep your SIM and CNIC details aligned, and spend the facility only on farm inputs. That careful preparation is what turns eligibility on paper into a card that works season after season.
Who is eligible for the Punjab Kisan Card in 2026?
A Punjab resident with a valid CNIC, holding 1 to 12.5 acres of Punjab Land Records Authority-verified agricultural land, with a SIM in their own name and no bank default, is eligible. Tenant farmers can apply with verified tenancy documents.
How much loan does the Kisan Card give per season?
The facility is Rs 30,000 per acre, up to a maximum of Rs 150,000 per season. A 2-acre farmer qualifies for up to Rs 60,000, and a 5-acre farmer reaches the Rs 150,000 ceiling.
Is the Kisan Card loan really interest-free?
Yes. You repay exactly what you used, with no markup or hidden service charge. The season runs for 6 months, with a 1-month grace period after it closes, and the government bears the markup cost.
Can a tenant farmer apply without owning land?
Yes, where the tenancy or lease is properly documented and verified. Genuine cultivators are not left out simply because the land paper is in someone else’s name, but undocumented tenancy claims will not pass verification.
What is the most common reason for refusal?
A bank default on record is the commonest reason, followed by land that cannot be verified in the applicant’s name. SIM mismatches, expired CNICs and land record errors are the other frequent causes.
Shahzad Sahil is the editor of lahorejobs24.com, covering government jobs, private jobs, bank jobs, results and education news for Lahore and Punjab, with information verified from official sources.